Back to Network







5
Shared Docs
3
Same-Page
6 / 5
Mentions
Document Mentions (5 shared documents)
3 mentions1 same-page
Page ?Same page
e appreciation of the yen, once again pushing the Bank of Japan’s (BOJ’s) 2% inflation target further into the futu
u of Labor Statistics BOE: Bank of England BOJ: Bank of Japan CAGR: compound annual growth rate CDS: credit de
conditions supportive of growth. While we expect the European Central Bank (ECB) to gradually shift to a more neutral stance
2 mentions1 same-page
Page HOUSE_OVERSIGHT_030842Same page
believe inflation comes after growth and therefore isn't a threat to this cycle of easy monetary policy. We expect the Fed, European Central Bank and Bank of Japan will continue to promote "easy money." There is going to be an inflation shock that will come with accelerating growth-we just don't see it next year
Page: HOUSE_OVERSIGHT_030842 →onomics team continues to believe inflation comes after growth and therefore isn't a threat to this cycle of easy monetary policy. We expect the Fed, European Central Bank and Bank of Japan will continue to promote "easy money." There is going to be an inflation shock that will come with accelerating growth-we just don'
Page: HOUSE_OVERSIGHT_030842 →2 mentions1 same-page
Page ?Same page
's "no new model to replace it." Domestic demand will prove an inadequate substitute. Central banks (the Federal Reserve, the European Central Bank, the Bank of Japan) have tried to fill the void with hyper-easy money policies. Smick fears damaging outcomes: currency wars as countries strive to capture greater sh
That's weakened, and there's "no new model to replace it." Domestic demand will prove an inadequate substitute. Central banks (the Federal Reserve, the European Central Bank, the Bank of Japan) have tried to fill the void with hyper-easy money policies. Smick fears damaging outcomes: currency wars as countries strive to
Sponsored
HOUSE_OVERSIGHT_024135 - HOUSE_OVERSIGHT_024178
<<Presentation Title>>
2 mentions
Page HOUSE_OVERSIGHT_024160
quality. ¢ The economic recovery fails to gain momentum in the second half of the year. Credit demand fails to improve further as some of the recent European Central Bank (ECB) data indicates. The ECB cuts rates. ¢ Further quantitative easing by the Fed would be supportive for Bunds and speaks for lower yields. & Negat
Page: HOUSE_OVERSIGHT_024160 →Page HOUSE_OVERSIGHT_024165
should profit in the medium term. e Longer-term debt issues and weak competitiveness of major exporters are hurting the Japanese economy. Therefore the Bank of Japan and Ministry of Finance will maintain an expansive policy and continue to try weaken the JPY. However, current positive growth dynamics are supportiv
Page: HOUSE_OVERSIGHT_024165 →Page HOUSE_OVERSIGHT_025250
Foreign Exchange We remain underweight the Japanese yen. The Japanese economy continues to weaken against its peers, leading to rising pressure for the Bank of Japan to engage in further quantitative easing. We have closed our preference for the Canadian dollar following its recent strength, and therefore close ou
Page: HOUSE_OVERSIGHT_025250 →Page HOUSE_OVERSIGHT_025275
tion of US Treasury and German Bund yields are important for EM fixed income spreads, especially for USD- and EUR-denominated bonds. Key date: Dec 6, European Central Bank meeting Capital flows The European debt crisis may lead to further periods of outflows and weaker prices, which could offer attractive entry levels
Page: HOUSE_OVERSIGHT_025275 →Sponsored
Mutual Connections (121)
Entities connected to both the Bank of Japan and the European Central Bank
Barack Obama
PERSON6 w/ the·20 w/ the
Marc Rich
PERSON5 w/ the·15 w/ the
George W. Bush
PERSON2 w/ the·18 w/ the
United Kingdom
LOCATION4 w/ the·13 w/ the
United States
LOCATION5 w/ the·11 w/ the
Frankfurt
LOCATION5 w/ the·9 w/ the
BaFin
ORGANIZATION3 w/ the·10 w/ the
JPMorgan Chase
ORGANIZATION4 w/ the·8 w/ the
the Prudential Regulation Authority
ORGANIZATION2 w/ the·9 w/ the
Malaysia
LOCATION7 w/ the·4 w/ the
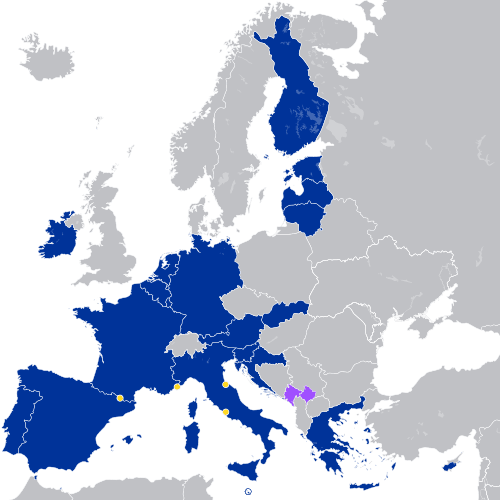
Eurozone
ORGANIZATION6 w/ the·5 w/ the
Michael Bloomberg
PERSON7 w/ the·3 w/ the
DB
Doug Band
PERSON4 w/ the·6 w/ the
Donald Trump
PERSON4 w/ the·6 w/ the
the Bank of England
ORGANIZATION4 w/ the·4 w/ the
Hungary
LOCATION5 w/ the·3 w/ the
U.S. Treasury
ORGANIZATION5 w/ the·3 w/ the
The Monetary Authority of Singapore
ORGANIZATION5 w/ the·3 w/ the
Belgium
LOCATION4 w/ the·4 w/ the
Luxembourg
LOCATION3 w/ the·4 w/ the