Back to Network
5
Shared Docs
2
Same-Page
5 / 5
Mentions
Document Mentions (5 shared documents)
HOUSE_OVERSIGHT_024135 - HOUSE_OVERSIGHT_024178
<<Presentation Title>>
2 mentions1 same-page
Page HOUSE_OVERSIGHT_024165Same page
should profit in the medium term. e Longer-term debt issues and weak competitiveness of major exporters are hurting the Japanese economy. Therefore the Bank of Japan and Ministry of Finance will maintain an expansive policy and continue to try weaken the JPY. However, current positive growth dynamics are supportiv
Page: HOUSE_OVERSIGHT_024165 →medium term. e Longer-term debt issues and weak competitiveness of major exporters are hurting the Japanese economy. Therefore the Bank of Japan and Ministry of Finance will maintain an expansive policy and continue to try weaken the JPY. However, current positive growth dynamics are supportive of the JPY. ¢ For com
Page: HOUSE_OVERSIGHT_024165 →2 mentions1 same-page
Page ?Same page
than trend shifts. • Last week, we raised our USD/JPY forecasts from a 2013 range of 75.85 to a range of 80-90. We have always been sceptical that the Bank of Japan would be able to drive up Japanese inflation and drive down real yields versus the US to power USD/JPY higher throughout 2013, but there is no deny
ties and Exchange Board of India. Thailand: JPMorgan Securities (Thailand) Limited is a member of the Stock Exchange of Thailand and is regulated by the Ministry of Finance and the Securities and Exchange Commission. Indonesia: PT E. Morgan Securities Indonesia is a member of the Indonesia Stock Exchange and is regulate
2 mentions
Page ?
ng about massive shifts in the fiscal stance here—the Ministry of Finance remains very much opposed to expanding the defici
Page HOUSE_OVERSIGHT_014414
d 1.9% in CY16 (Chart 13). One explanation is that private consumption is simply being underestimated in demand- side GDP statistics: researchers at the Bank of Japan recently produced experimental supply-side estimates of GDP that were significantly higher than existing expenditure- side statistics. We find the Bo
Page: HOUSE_OVERSIGHT_014414 →Sponsored
Page HOUSE_OVERSIGHT_025250
Foreign Exchange We remain underweight the Japanese yen. The Japanese economy continues to weaken against its peers, leading to rising pressure for the Bank of Japan to engage in further quantitative easing. We have closed our preference for the Canadian dollar following its recent strength, and therefore close ou
Page: HOUSE_OVERSIGHT_025250 →Page HOUSE_OVERSIGHT_025277
ues and weak competitiveness of major exporters are hurting the Japanese economy and PMls have disappointed. We therefore think the Bank of Japan and Ministry of Finance will maintain an expansive policy bias and continue trying to weaken the JPY. We are underweight JPY. ¢ For commodity currencies, the AUD and NZD co
Page: HOUSE_OVERSIGHT_025277 →Page HOUSE_OVERSIGHT_026573
lar to QE itself. Beyond that, this is another small step towards perceptions that monetary policy is no longer independent from fiscal policy, like the Bank of Japan’s joint statement with two government ministers last month. Nobody knows the tipping point at which these perceptions feed into much higher inflation e
Page: HOUSE_OVERSIGHT_026573 →Page HOUSE_OVERSIGHT_026578
ities and Exchange Board of India. Thailand: JPMorgan Securities (Thailand) Limited is a member of the Stock Exchange of Thailand and is regulated by the Ministry of Finance and the Securities and Exchange Commission. Indonesia: PT J.P. Morgan Securities Indonesia is a member of the Indonesia Stock Exchange and is regulat
Page: HOUSE_OVERSIGHT_026578 →Sponsored
Mutual Connections (173)
Entities connected to both the Bank of Japan and the Ministry of Finance
Malaysia
LOCATION7 w/ the·21 w/ the
Philippines
LOCATION4 w/ the·19 w/ the
JPMorgan Chase
ORGANIZATION4 w/ the·17 w/ the
the Securities and Futures Commission
ORGANIZATION3 w/ the·16 w/ the
the Central Bank of Brazil
ORGANIZATION3 w/ the·16 w/ the
New Zealand
LOCATION2 w/ the·17 w/ the
the Philippine Stock Exchange
ORGANIZATION2 w/ the·16 w/ the
the Mexican Stock Exchange
ORGANIZATION2 w/ the·16 w/ the
the Stock Exchange of Thailand
ORGANIZATION2 w/ the·16 w/ the
Bombay Stock Exchange Limited
ORGANIZATION2 w/ the·16 w/ the
the Taiwan Securities and Futures Bureau
ORGANIZATION2 w/ the·16 w/ the
the Indonesia Stock Exchange
ORGANIZATION2 w/ the·16 w/ the
Frankfurt
LOCATION5 w/ the·12 w/ the
Saudi Arabia
LOCATION3 w/ the·14 w/ the
Kanto Local Finance Bureau
ORGANIZATION2 w/ the·15 w/ the
Barack Obama
PERSON6 w/ the·10 w/ the
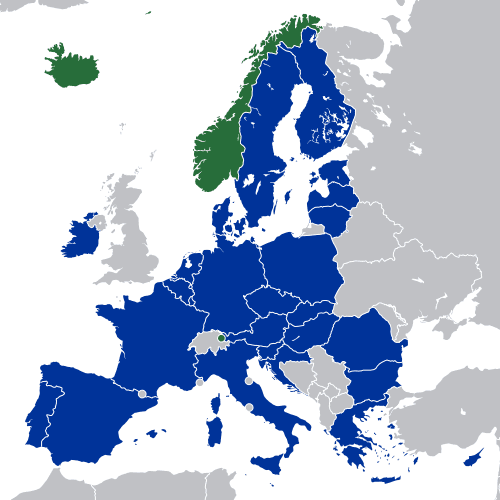
European Economic Area
LOCATION2 w/ the·14 w/ the
the Capital Market Authority
ORGANIZATION2 w/ the·13 w/ the
Japan Investment Advisers Association
ORGANIZATION2 w/ the·13 w/ the
Michael Bloomberg
PERSON7 w/ the·7 w/ the