Back to Network

5
Shared Docs
5
Same-Page
5 / 5
Mentions
Document Mentions (5 shared documents)
2 mentions1 same-page
Page ?Same page
VESTMENT FOR AN INDEFINITE PERIOD OF TIME. EACH HOLDER OF INTERESTS WILL BE REQUIRED UPON REQUEST BY THE
t Limited Partner, and the amount so included in income will be treated as a deduction generated by the Access Fund in the following taxable year. Deductibility of Access Fund Expenses by Non-Corporate Limited Partners. Prospective investors who are individuals or certain closely held corporations should be aware that th
Sponsored
2 mentions1 same-page
Page ?Same page
VESTMENT FOR AN INDEFINITE PERIOD OF TIME. EACH HOLDER OF INTERESTS WILL BE REQUIRED UPON REQUEST BY THE
t Limited Partner, and the amount so included in income will be treated as a deduction generated by the Access Fund in the following taxable year. Deductibility of Access Fund Expenses by Non-Corporate Limited Partners. Prospective investors who are individuals or certain closely held corporations should be aware that th
Sponsored
Mutual Connections (79)
Entities connected to both Eric Holder and Deductibility of Access Fund
United States
LOCATION201 w/ Eric·5 w/ Deductibility
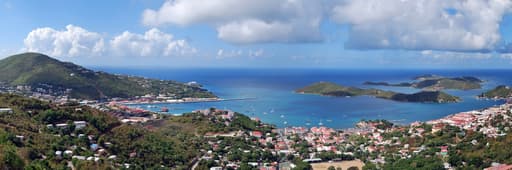
U.S. Virgin Islands
LOCATION127 w/ Eric·5 w/ Deductibility
Paul Volcker
PERSON94 w/ Eric·5 w/ Deductibility
Puerto Rico
LOCATION47 w/ Eric·5 w/ Deductibility
Cayman Islands
LOCATION40 w/ Eric·5 w/ Deductibility
the U.S. Investment Company Act
ORGANIZATION29 w/ Eric·5 w/ Deductibility
the District of Columbia
LOCATION26 w/ Eric·5 w/ Deductibility
Non-Corporate Limited Partners
ORGANIZATION5 w/ Eric·24 w/ Deductibility
Norway
LOCATION24 w/ Eric·5 w/ Deductibility
United Kingdom
LOCATION23 w/ Eric·5 w/ Deductibility
Belgium
LOCATION22 w/ Eric·5 w/ Deductibility
United States District Court
ORGANIZATION21 w/ Eric·5 w/ Deductibility
Luxembourg
LOCATION20 w/ Eric·5 w/ Deductibility
Keogh
ORGANIZATION20 w/ Eric·5 w/ Deductibility
Ireland
LOCATION19 w/ Eric·5 w/ Deductibility
Cayman
LOCATION19 w/ Eric·5 w/ Deductibility
Hungary
LOCATION18 w/ Eric·5 w/ Deductibility
Bulgaria
LOCATION16 w/ Eric·5 w/ Deductibility
Malta
LOCATION15 w/ Eric·5 w/ Deductibility
Denmark
LOCATION15 w/ Eric·5 w/ Deductibility