Back to Network


5
Shared Docs
5
Same-Page
5 / 5
Mentions
Document Mentions (5 shared documents)
2 mentions1 same-page
Page ?Same page
tal combined voting power or total value of the corporation's stock on any day during any taxable year. If the Access Fund invests in a CFC and is a United States Shareholder, its Limited Partners who are U.S. persons will be subject to tax under the CFC rules. As a result, each such Limited Partner must inc
he Bipartisan Budget Act of 2015, legislation was enacted that significantly changes the rules for U.S. federal income tax audits of partnerships (the "BBA Rules"). Such audits will continue to be conducted at the partnership level, but with respect to U.S. federal income tax returns for taxable years begin
Sponsored
2 mentions1 same-page
Page ?Same page
tal combined voting power or total value of the corporation's stock on any day during any taxable year. If the Access Fund invests in a CFC and is a United States Shareholder, its Limited Partners who are U.S. persons will be subject to tax under the CFC rules. As a result, each such Limited Partner must inc
he Bipartisan Budget Act of 2015, legislation was enacted that significantly changes the rules for U.S. federal income tax audits of partnerships (the "BBA Rules"). Such audits will continue to be conducted at the partnership level, but with respect to U.S. federal income tax returns for taxable years begin
Sponsored
Mutual Connections (78)
Entities connected to both United States and the "BBA Rules
U.S. Virgin Islands
LOCATION341 w/ United·5 w/ the
United Kingdom
LOCATION276 w/ United·5 w/ the
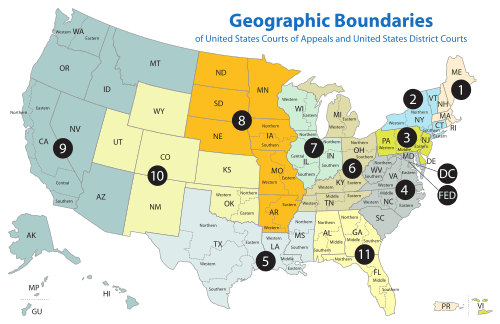
United States District Court
ORGANIZATION238 w/ United·5 w/ the
Eric Holder
PERSON201 w/ United·5 w/ the
Puerto Rico
LOCATION187 w/ United·5 w/ the
the District of Columbia
LOCATION162 w/ United·5 w/ the
European Union
ORGANIZATION112 w/ United·5 w/ the
Denmark
LOCATION110 w/ United·5 w/ the
Norway
LOCATION95 w/ United·5 w/ the
Belgium
LOCATION90 w/ United·5 w/ the
Glendower
LOCATION87 w/ United·5 w/ the
Glendower Capital
ORGANIZATION83 w/ United·5 w/ the
Cayman
LOCATION74 w/ United·5 w/ the
Marla Maples
PERSON74 w/ United·5 w/ the
Finland
LOCATION72 w/ United·5 w/ the
Hungary
LOCATION64 w/ United·5 w/ the
Luxembourg
LOCATION60 w/ United·5 w/ the
Cayman Islands
LOCATION58 w/ United·5 w/ the
Calder
ORGANIZATION58 w/ United·5 w/ the
Ireland
LOCATION55 w/ United·5 w/ the