Back to Network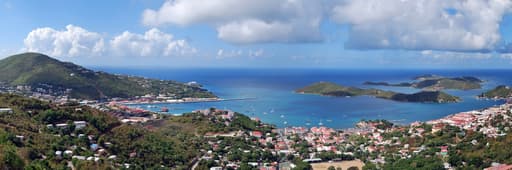


5
Shared Docs
5
Same-Page
8 / 5
Mentions
Document Mentions (5 shared documents)
4 mentions1 same-page
Page ?Same page
e exempt company provisions, their technical application and requirements, and their practical application as a tax planning mechanism for selected non-United States owners. I. Historical, Policy and Legislative Background Formulation of Territorial Policy and Territorial Tax Policy The United States has sovere
Guam, American Samoa and the Northern Marianas as foreign corporations, while individual U.S. citizens resident in those jurisdictions are taxed by the United States on their worldwide income except that income from territorial sources is exempt While not directly eliminating the mirror systems in these territori
hicle for establishing a foreign (non-U.S.) owned exempt Insurance Company in the U.S. Virgin Islands, an exempt insurer may also be established by a United States person using a standard U.S. Virgin Islands corporation. However, it should be noted that changes in federal tax law in the 1980's, and the impositi
ns (i.e., income which is not exempt from tax), an income tax return need not be filed with either the Virgin Islands Bureau of Internal Revenue or the United States Internal Revenue Service. Establishment of a U.S. Virgin Islands Exempt Company Organizing a U.S. Virgin Islands exempt company is simple and may usually be accomplished w
3 mentions1 same-page
Page ?Same page
arbarm Traraation Material United States tax consequences It we make a clistnloutson from current a OCCUMUISICO earnings end profits, as compasafor United Slates federal income lax exposes. such dstribubon will generally be taxable to holders d our Class A corrrnon stock n the current period as ordrery ncorne
hat a portion of ors distributions to holders of or Cass A coehrhOn stock may exceed our current and accumulated earn rgs and profits as computed fa Unted States federal none tax purposes and therefore constitute a non-taxable return of captal to the extent °dance:left base in our Cass A common stock, no aseo
t United States federal income laxes in the near term Noserter, the 3V3sOblity of the NOLs and NOL canyforwards could be reduced or limited ether by the United States Internal Revenue Service or 'IRS,' (pursuers to a successful challenge in a tax suet or otherwise) or as a result cf an 'ownership change' or a change in law Any such reduct
2 mentions1 same-page
Page ?Same page
as defined in 18 U.S.C. § 2423(f), with minor females, in violation of Title 18, United States Code, Section 2423(b); all in violation of Title 18, United States Code, Section 2423(e); (c) used a facility or means of interstate or foreign commerce to knowingly persuade, induce, or entice minor females, inclu
cuting agencies relating to the State criminal case against you or the Federal investigation against you. EFTA00729650 8. Tax returns filed with the United States Internal Revenue Service from 2002 through the present. 9. Photocopies of your passport, including any supplemental pages reflecting visa's or entries to locations outsid
Sponsored
2 mentions1 same-page
Page ?Same page
VCs are not stock in the Issuer. However, no assurances can be given in this regard, and it is possible that a U.S. Holder of SVCs may be treated as a United States Shareholder. If the SVCs were treated as stock in the Issuer and the Issuer were treated as a CFC, a U.S. Holder of SVCs that is treated as a Unite
tegories of Non-Reporting FIs are set out in an annex to the US IGA. A Reporting Fl is not required to enter into a separate agreement directly with the United States Internal Revenue Service (IRS), but must: (i) register with the IRS to obtain a Global Intermediary Identification Number; (ii) register with the Cayman Islands Tax Informa
2 mentions1 same-page
Page ?Same page
ed as trusts for U.S. federal income tax purposes are subject to special rules). If the Fund is not engaged in the conduct of a trade or business in the United States, Non-U.S. Partners in the Fund's shares of income and gains from sources other than the United States (e.g., generally, interest or dividends paid b
tegories of Non-Reporting FIs are set out in an annex to the US IGA. A Reporting Fl is not required to enter into a separate agreement directly with the United States Internal Revenue Service ("IRS'), but must: (i) register with the IRS to obtain a Global Intermediary Identification Number; (ii) register with the Cayman Islands Tax Infor
Sponsored
Mutual Connections (57)
Entities connected to both United States and the United States Internal Revenue Service
U.S. Virgin Islands
LOCATION341 w/ United·2 w/ the
Cayman
LOCATION74 w/ United·2 w/ the
the Cayman Islands
LOCATION44 w/ United·2 w/ the
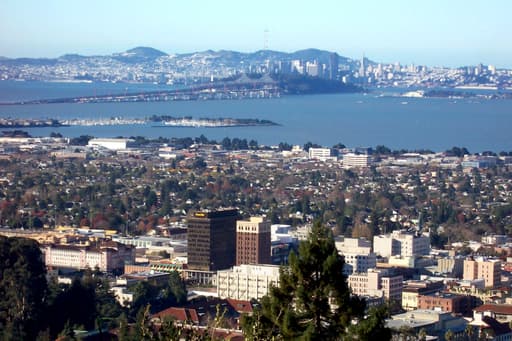
Berkeley
LOCATION44 w/ United·2 w/ the
RESIDENCE
ORGANIZATION16 w/ United·2 w/ the
University of California
ORGANIZATION16 w/ United·2 w/ the
Reliance
ORGANIZATION13 w/ United·2 w/ the
LO
Louie
PERSON9 w/ United·2 w/ the
the Cayman Islands Monetary Authority
ORGANIZATION9 w/ United·2 w/ the
Grand Cayman
LOCATION8 w/ United·2 w/ the
the U.S. Investment Advisers Act
ORGANIZATION8 w/ United·2 w/ the
Occidental College
ORGANIZATION8 w/ United·2 w/ the
the British Virgin Islands
LOCATION7 w/ United·2 w/ the
Jefferies
ORGANIZATION7 w/ United·2 w/ the
AN
Andra
PERSON6 w/ United·2 w/ the
Misconduct
ORGANIZATION6 w/ United·2 w/ the
the '
ORGANIZATION5 w/ United·2 w/ the
Indemnitees
ORGANIZATION4 w/ United·2 w/ the
UNITED STATES FEDERAL INCOME TAX CONSIDERATIONS
ORGANIZATION4 w/ United·2 w/ the
White Oak
LOCATION4 w/ United·2 w/ the