Back to Network











5
Shared Docs
0
Same-Page
5 / 6
Mentions
Document Mentions (5 shared documents)
Page ?
e appreciation of the yen, once again pushing the Bank of Japan’s (BOJ’s) 2% inflation target further into the futu
u of Labor Statistics BOE: Bank of England BOJ: Bank of Japan CAGR: compound annual growth rate CDS: credit de
Page HOUSE_OVERSIGHT_014533
ctor Matheus Dibo Vice President Mary Catherine Rich Vice President This material represents the view
Page: HOUSE_OVERSIGHT_014533 →2 mentions
Page HOUSE_OVERSIGHT_014732
rowing disparity of income and wealth between the rich and the poor (Chart 2), and the loss of national
Page: HOUSE_OVERSIGHT_014732 →Page HOUSE_OVERSIGHT_014734
75 70 65 60 55 50 1/1/2010 5/1/2011 8/4/2012 = 1/1/2014) 5/1/2015 = 9/1/2016 Source: BofA Merrill Lynch Global Research true against the JPY given the Bank of Japan is pegging 10y JGB yields at zero. We are cognizant of the possibility that the willingness of Japanese investors — who have already bought record am
Page: HOUSE_OVERSIGHT_014734 →2 mentions
Page HOUSE_OVERSIGHT_014987
la variance as investors can avoid paying for the rich HSCEI convexity below the 70% barrier. The trade
Page: HOUSE_OVERSIGHT_014987 →Page HOUSE_OVERSIGHT_014989
last week’s biggest losers were Korea’s KOSPI and India’s NIFTY, which each returned -0.8% week-over-week. In Japan, the Nikkei fell 0.3%. On Friday, the Bank of Japan (BoJ) left its monetary policy unchanged—it will continue to control the yield curve via its negative benchmark rate and its asset purchasing program
Page: HOUSE_OVERSIGHT_014989 →Sponsored
HOUSE_OVERSIGHT_024135 - HOUSE_OVERSIGHT_024178
<<Presentation Title>>
2 mentions
Page HOUSE_OVERSIGHT_024154
would advise a tilt in EM portfolios toward cash-rich and faster- growing Asia. Emerging market countr
Page: HOUSE_OVERSIGHT_024154 →Page HOUSE_OVERSIGHT_024165
should profit in the medium term. e Longer-term debt issues and weak competitiveness of major exporters are hurting the Japanese economy. Therefore the Bank of Japan and Ministry of Finance will maintain an expansive policy and continue to try weaken the JPY. However, current positive growth dynamics are supportiv
Page: HOUSE_OVERSIGHT_024165 →Page HOUSE_OVERSIGHT_025250
Foreign Exchange We remain underweight the Japanese yen. The Japanese economy continues to weaken against its peers, leading to rising pressure for the Bank of Japan to engage in further quantitative easing. We have closed our preference for the Canadian dollar following its recent strength, and therefore close ou
Page: HOUSE_OVERSIGHT_025250 →Page HOUSE_OVERSIGHT_025266
would advise that EM portfolios tilt toward cash-rich and faster- growing Asia. Country preferences wi
Page: HOUSE_OVERSIGHT_025266 →Sponsored
Mutual Connections (182)
Entities connected to both Marc Rich and the Bank of Japan
George W. Bush
PERSON853 w/ Marc·2 w/ the
John F. Kennedy
PERSON836 w/ Marc·2 w/ the
Donald Trump
PERSON730 w/ Marc·4 w/ the
United States
LOCATION626 w/ Marc·5 w/ the
JPMorgan Chase
ORGANIZATION509 w/ Marc·4 w/ the
Barack Obama
PERSON373 w/ Marc·6 w/ the
DB
Doug Band
PERSON335 w/ Marc·4 w/ the
Bloomberg L.P.
ORGANIZATION320 w/ Marc·2 w/ the
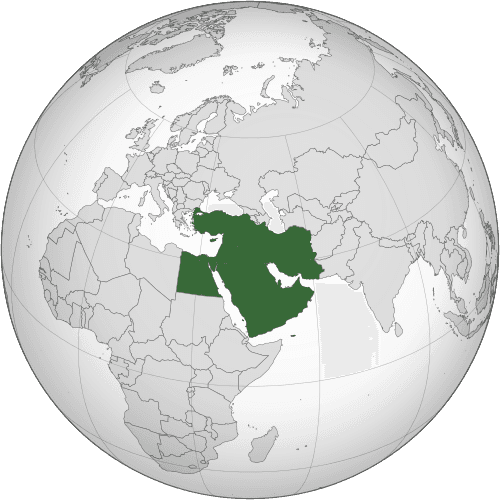
Middle East
LOCATION136 w/ Marc·2 w/ the
Philippines
LOCATION123 w/ Marc·4 w/ the
United Kingdom
LOCATION106 w/ Marc·4 w/ the
Eric Holder
PERSON99 w/ Marc·4 w/ the
Xi Jinping
PERSON96 w/ Marc·2 w/ the
Venezuela
LOCATION90 w/ Marc·3 w/ the
North America
LOCATION85 w/ Marc·3 w/ the
U.S. Treasury
ORGANIZATION81 w/ Marc·5 w/ the
Columbia University
LOCATION80 w/ Marc·3 w/ the
Tokyo
LOCATION80 w/ Marc·2 w/ the
Norway
LOCATION72 w/ Marc·2 w/ the
Michael Bloomberg
PERSON65 w/ Marc·7 w/ the