Back to Network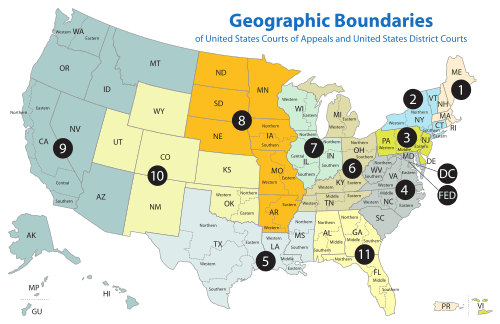
5
Shared Docs
5
Same-Page
5 / 5
Mentions
Document Mentions (5 shared documents)
2 mentions1 same-page
Page ?Same page
e General Partner or the Limited Partners will have an opportunity to participate in the control, management or operations of the Underlying Fund. Investment Concentration. The Access Fund will invest solely in the Underlying Fund (and in coinvestments, if any, with the Underlying Fund or its respective affiliates). B
lling to receive material amounts of UBTI. U.S. Tax-Exempt Investors that are not willing to receive material amounts of UBTI should not invest in the Access Fund A Feeder Fund may be organized to accommodate certain qualified U.S. Tax-Exempt Investors who do not wish to receive UBTI. United States Foreign Tax Credits. Su
2 mentions1 same-page
Page ?Same page
e General Partner or the Limited Partners will have an opportunity to participate in the control, management or operations of the Underlying Fund. Investment Concentration. The Access Fund will invest solely in the Underlying Fund (and in coinvestments, if any, with the Underlying Fund or its respective affiliates). B
lling to receive material amounts of UBTI. U.S. Tax-Exempt Investors that are not willing to receive material amounts of UBTI should not invest in the Access Fund A Feeder Fund may be organized to accommodate certain qualified U.S. Tax-Exempt Investors who do not wish to receive UBTI. United States Foreign Tax Credits. Su
2 mentions1 same-page
Page ?Same page
e General Partner or the Limited Partners will have an opportunity to participate in the control, management or operations of the Underlying Fund. Investment Concentration. The Access Fund will invest solely in the Underlying Fund (and in coinvestments, if any, with the Underlying Fund or its respective affiliates). B
lling to receive material amounts of UBTI. U.S. Tax-Exempt Investors that are not willing to receive material amounts of UBTI should not invest in the Access Fund A Feeder Fund may be organized to accommodate certain qualified U.S. Tax-Exempt Investors who do not wish to receive UBTI. United States Foreign Tax Credits. Su
Sponsored
2 mentions1 same-page
Page ?Same page
e General Partner or the Limited Partners will have an opportunity to participate in the control, management or operations of the Underlying Fund. Investment Concentration. The Access Fund will invest solely in the Underlying Fund (and in coinvestments, if any, with the Underlying Fund or its respective affiliates). B
lling to receive material amounts of UBTI. U.S. Tax-Exempt Investors that are not willing to receive material amounts of UBTI should not invest in the Access Fund A Feeder Fund may be organized to accommodate certain qualified U.S. Tax-Exempt Investors who do not wish to receive UBTI. United States Foreign Tax Credits. Su
2 mentions1 same-page
Page ?Same page
e General Partner or the Limited Partners will have an opportunity to participate in the control, management or operations of the Underlying Fund. Investment Concentration. The Access Fund will invest solely in the Underlying Fund (and in coinvestments, if any, with the Underlying Fund or its respective affiliates). B
lling to receive material amounts of UBTI. U.S. Tax-Exempt Investors that are not willing to receive material amounts of UBTI should not invest in the Access Fund A Feeder Fund may be organized to accommodate certain qualified U.S. Tax-Exempt Investors who do not wish to receive UBTI. United States Foreign Tax Credits. Su
Sponsored
Mutual Connections (77)
Entities connected to both Investment Concentration and the Access Fund A Feeder Fund
the District of Massachusetts
LOCATION23 w/ Investment·5 w/ the
United States District Court
ORGANIZATION23 w/ Investment·5 w/ the
the First Circuit
ORGANIZATION23 w/ Investment·5 w/ the
Glendower
LOCATION23 w/ Investment·5 w/ the
U.S. Virgin Islands
LOCATION5 w/ Investment·5 w/ the
United States
LOCATION5 w/ Investment·5 w/ the
United Kingdom
LOCATION5 w/ Investment·5 w/ the
Eric Holder
PERSON5 w/ Investment·5 w/ the
Paul Volcker
PERSON5 w/ Investment·5 w/ the
Norway
LOCATION5 w/ Investment·5 w/ the
Hungary
LOCATION5 w/ Investment·5 w/ the
Belgium
LOCATION5 w/ Investment·5 w/ the
Estonia
LOCATION5 w/ Investment·5 w/ the
Denmark
LOCATION5 w/ Investment·5 w/ the
Finland
LOCATION5 w/ Investment·5 w/ the
European Union
ORGANIZATION5 w/ Investment·5 w/ the
Romania
LOCATION5 w/ Investment·5 w/ the
Lithuania
LOCATION5 w/ Investment·5 w/ the
Cyprus
LOCATION5 w/ Investment·5 w/ the
Northern Ireland
LOCATION5 w/ Investment·5 w/ the