Back to Network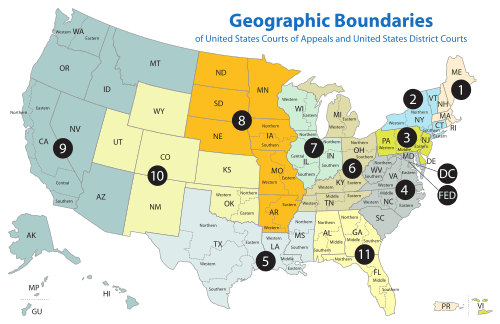


5
Shared Docs
5
Same-Page
5 / 5
Mentions
Document Mentions (5 shared documents)
2 mentions1 same-page
Page ?Same page
e General Partner or the Limited Partners will have an opportunity to participate in the control, management or operations of the Underlying Fund. Investment Concentration. The Access Fund will invest solely in the Underlying Fund (and in coinvestments, if any, with the Underlying Fund or its respective affiliates). B
es for three years and may carry forward such losses for five years; non-corporate taxpayers may carry forward unused capital losses indefinitely. Tax Treatment of Investments. In general and except as discussed below, the Access Fund expects that its gains will be treated as capital gain for U.S. federal income tax purpo
Sponsored
2 mentions1 same-page
Page ?Same page
e General Partner or the Limited Partners will have an opportunity to participate in the control, management or operations of the Underlying Fund. Investment Concentration. The Access Fund will invest solely in the Underlying Fund (and in coinvestments, if any, with the Underlying Fund or its respective affiliates). B
es for three years and may carry forward such losses for five years; non-corporate taxpayers may carry forward unused capital losses indefinitely. Tax Treatment of Investments. In general and except as discussed below, the Access Fund expects that its gains will be treated as capital gain for U.S. federal income tax purpo
Sponsored
Mutual Connections (77)
Entities connected to both Investment Concentration and Tax Treatment of Investments
the First Circuit
ORGANIZATION23 w/ Investment·5 w/ Tax
United States District Court
ORGANIZATION23 w/ Investment·5 w/ Tax
Glendower
LOCATION23 w/ Investment·5 w/ Tax
the District of Massachusetts
LOCATION23 w/ Investment·5 w/ Tax
Paul Volcker
PERSON5 w/ Investment·5 w/ Tax
Norway
LOCATION5 w/ Investment·5 w/ Tax
Hungary
LOCATION5 w/ Investment·5 w/ Tax
Belgium
LOCATION5 w/ Investment·5 w/ Tax
Estonia
LOCATION5 w/ Investment·5 w/ Tax
Denmark
LOCATION5 w/ Investment·5 w/ Tax
Finland
LOCATION5 w/ Investment·5 w/ Tax
European Union
ORGANIZATION5 w/ Investment·5 w/ Tax
Romania
LOCATION5 w/ Investment·5 w/ Tax
Lithuania
LOCATION5 w/ Investment·5 w/ Tax
Cyprus
LOCATION5 w/ Investment·5 w/ Tax
Northern Ireland
LOCATION5 w/ Investment·5 w/ Tax
Marla Maples
PERSON5 w/ Investment·5 w/ Tax
Croatia
LOCATION5 w/ Investment·5 w/ Tax
Slovakia
LOCATION5 w/ Investment·5 w/ Tax
Puerto Rico
LOCATION5 w/ Investment·5 w/ Tax