Back to Network







5
Shared Docs
5
Same-Page
5 / 5
Mentions
Document Mentions (5 shared documents)
2 mentions1 same-page
Page ?Same page
ners"). The Access Fund is designed for investors ("Investors") that are either (A) U.S. taxable investors or (B) investors that are pension plans, Keogh plans, individual retirement accounts, tax-exempt institutions and other tax-exempt limited partners ("U.S. Tax-Exempt Investors") that are willin
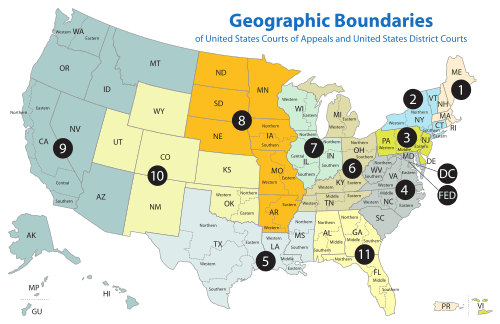
loyer pension plans and withdrawal liability from union-sponsored multiemployer pension plans. In July 2013, the U.S. Federal Court of Appeals for the First Circuit held that the portfolio company management activities of a private equity fund could cause the fund to be regarded for ERISA controlled group lia
Sponsored
2 mentions1 same-page
Page ?Same page
ners"). The Access Fund is designed for investors ("Investors") that are either (A) U.S. taxable investors or (B) investors that are pension plans, Keogh plans, individual retirement accounts, tax-exempt institutions and other tax-exempt limited partners ("U.S. Tax-Exempt Investors") that are willin
loyer pension plans and withdrawal liability from union-sponsored multiemployer pension plans. In July 2013, the U.S. Federal Court of Appeals for the First Circuit held that the portfolio company management activities of a private equity fund could cause the fund to be regarded for ERISA controlled group lia
Sponsored
Mutual Connections (123)
Entities connected to both Keogh and the First Circuit
Access Fund
ORGANIZATION40 w/ Keogh·18 w/ the
United States
LOCATION44 w/ Keogh·12 w/ the
Glendower
LOCATION13 w/ Keogh·23 w/ the
iCapital
ORGANIZATION27 w/ Keogh·5 w/ the
United States District Court
ORGANIZATION5 w/ Keogh·27 w/ the
Investment Concentration
ORGANIZATION5 w/ Keogh·23 w/ the
the District of Massachusetts
LOCATION5 w/ Keogh·23 w/ the
United Kingdom
LOCATION21 w/ Keogh·6 w/ the
Eric Holder
PERSON20 w/ Keogh·6 w/ the
Jeffrey Epstein
PERSON16 w/ Keogh·10 w/ the
Cayman
LOCATION21 w/ Keogh·5 w/ the
Ghislaine Maxwell
PERSON18 w/ Keogh·7 w/ the
George W. Bush
PERSON20 w/ Keogh·5 w/ the
Luxembourg
LOCATION19 w/ Keogh·5 w/ the
the District of Columbia
LOCATION15 w/ Keogh·5 w/ the
Belgium
LOCATION14 w/ Keogh·5 w/ the
New York
LOCATION16 w/ Keogh·3 w/ the
Ireland
LOCATION14 w/ Keogh·5 w/ the
Finland
LOCATION13 w/ Keogh·5 w/ the
Glendower Capital
ORGANIZATION13 w/ Keogh·5 w/ the