Back to Network














6
Shared Docs
2
Same-Page
7 / 8
Mentions
Document Mentions (6 shared documents)
2 mentions1 same-page
Page ?Same page
c adjustment in China are contributing to the current fall in investment, burdening industrials - more so in Europe than in the. United States. ()U.S. Treasuries (10-year) We are neutral on all U.S. Treasury maturities. Although we still believe that there will be an acceleration in economic growth In the s
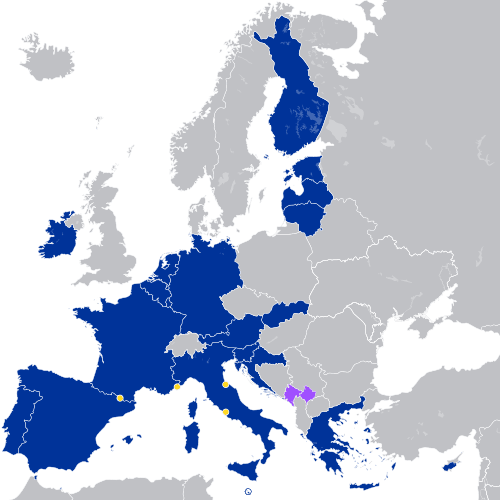
iigivvirmcwo Wee Investment traffic lights Our tactical and strategic view *Eurozone (equities) While we stay neutral on Europe. we upgrade the Eurozone to overweight. The danger of a "Grexit- appears to have passed its peak so that investors can again focus on corporate data which should benefit f
2 mentions1 same-page
Page ?Same page
balance is on a recovery path over the last one year Figure 2: as non-treasury portfolio outflows have turned positive Source: DB FX Research and US Treasury Source: DB FX Research and US Treasury Figure 3: The private basis balance has been diverging from the overall balance Figure 4: as official infl
ies from the IMF we calculate that German exports could be reduced by as much as EUR 3.3bn per year. In recent years, German exports to outside the Eurozone have grown as the economy has responded to weak demand in the single currency area. Germany's relatively strong growth compared the rest of the Eur
Page HOUSE_OVERSIGHT_014537
k 26 Pace of Federal Reserve Tightening 27 Low Expectations of a US Recession 28 29 30 30 31 33 Rising Influence of Populist Parties in the Eurozone Geopolitical Hot Spots Get Hotter Terrorism Escalates Cyberattacks Continue China Submerges Under Its Debt Burden and Capital Outflows US-China Re
Page: HOUSE_OVERSIGHT_014537 →Page HOUSE_OVERSIGHT_014552
Institution has called the “fiscal fights of the Obama administration.” The first fiscal fight resulted in the Standard and Poor’s (S&P) downgrade of US Treasury debt in August 2011. The equity markets, as measured by the S&P 500 Index, dropped about 19% between April and October of 2011. Taken together, the
Page: HOUSE_OVERSIGHT_014552 →Page HOUSE_OVERSIGHT_014558
wth of 4.6%, aided by healthy domestic growth, and a particularly well-capitalized® banking sector that has a lower nonperforming loan ratio than the Eurozone bank average. Furthermore, Spain is unlikely to face the same political uncertainty as Germany, France and Italy in 2017. We expect high single-digit
Page: HOUSE_OVERSIGHT_014558 →Sponsored
3 mentions
Page HOUSE_OVERSIGHT_014736
ad | 16 November 2016 HOUSE_OVERSIGHT_014735 --- PAGE BREAK --- target. It is possible that Trump’s election could weaken fiscal discipline in the Eurozone over the medium term, but we are more concerned by the non-trivial risk that the ECB may disappoint in the December meeting by either not extending q
Page: HOUSE_OVERSIGHT_014736 →Page HOUSE_OVERSIGHT_014738
=== 6m change in 30y real rates (RHS, inverted == USGGT10Y Index (R1) 5y5 | rates scale, %4) yoy real ra Source: BofA Merrill Lynch Global Research, US Treasury The BAML multi asset strategy index is not representative of all isk-parity funds. Si : BofA Merrill Lynch Global R h Source: BofA Merrill Lynch Glo
Page: HOUSE_OVERSIGHT_014738 →Page HOUSE_OVERSIGHT_014739
19). First, given USD/JPY’s significant correlation with 10Y yield differentials (>60%}, the anchoring of 10Y yields will further weigh on the Yen as US Treasury yields rise. Second, further Japanese fiscal stimulus will successfully lower real yields through higher breakeven rates of inflation while nominal y
Page: HOUSE_OVERSIGHT_014739 →Page HOUSE_OVERSIGHT_025250
important contributor to US GDP growth. Growth has also begun to pick up in key areas of the emerging markets, including China and Brazil. While the Eurozone economy remains weak, we expect Q3 2012 to mark the bottom, and that growth will begin to get "less bad" from Q4 2012. Equities Equity markets have
Page: HOUSE_OVERSIGHT_025250 →Page HOUSE_OVERSIGHT_025255
continue to tap the primary market if they ask for a support program? ¢ How much more support will Greece receive and will it be able to stay in the Eurozone next year? CIO View (Probability: 70%*) Austerity and weak growth ¢ We think the Eurozone economy troughed in 3Q. We expect flattish growth in 4Q 20
Page: HOUSE_OVERSIGHT_025255 →Page HOUSE_OVERSIGHT_025275
uld spike. Note: Scenarios refer to global economic scenarios (see slide 7) What we're watching Why it matters Core market yields The direction of US Treasury and German Bund yields are important for EM fixed income spreads, especially for USD- and EUR-denominated bonds. Key date: Dec 6, European Central Ba
Page: HOUSE_OVERSIGHT_025275 →HOUSE_OVERSIGHT_024135 - HOUSE_OVERSIGHT_024178
<<Presentation Title>>
2 mentions
Page HOUSE_OVERSIGHT_024138
36 UBS Economy The successful formation of a Greek government after the June 17 elections has reduced the risk of an imminent Greek exit from the Eurozone. However, the Euro debt crisis persists, and further reform and consolidation efforts in Spain and Italy are needed. In the US, economic data weakene
Page: HOUSE_OVERSIGHT_024138 →Page HOUSE_OVERSIGHT_024158
kets over the medium term. Valuations remain attractive, and the potential for spreads to trend lower should more than offset the gradual increase in US Treasury yields in the quarters ahead. We continue to prefer increasing exposure to corporate bonds while keeping existing investments in sovereign bonds. 36
Page: HOUSE_OVERSIGHT_024158 →Sponsored
Mutual Connections (330)
Entities connected to both U.S. Treasury and Eurozone
Jeffrey Epstein
PERSON232 w/ U.S.·27 w/ Eurozone
United States
LOCATION197 w/ U.S.·12 w/ Eurozone
Donald Trump
PERSON139 w/ U.S.·9 w/ Eurozone
George W. Bush
PERSON138 w/ U.S.·7 w/ Eurozone
Ghislaine Maxwell
PERSON135 w/ U.S.·3 w/ Eurozone
Barack Obama
PERSON107 w/ U.S.·17 w/ Eurozone
Bloomberg L.P.
ORGANIZATION92 w/ U.S.·15 w/ Eurozone
Bill Clinton
PERSON88 w/ U.S.·4 w/ Eurozone
Marc Rich
PERSON81 w/ U.S.·8 w/ Eurozone
Joe Biden
PERSON84 w/ U.S.·3 w/ Eurozone
Vicky Ward
PERSON82 w/ U.S.·3 w/ Eurozone
New York
LOCATION79 w/ U.S.·2 w/ Eurozone
DB
Doug Band
PERSON69 w/ U.S.·6 w/ Eurozone
Prince Charles
PERSON71 w/ U.S.·2 w/ Eurozone
Stephen Hawking
PERSON68 w/ U.S.·2 w/ Eurozone
UBS AG
ORGANIZATION67 w/ U.S.·2 w/ Eurozone
United Kingdom
LOCATION53 w/ U.S.·13 w/ Eurozone
Paul Ryan
PERSON63 w/ U.S.·2 w/ Eurozone
Vladimir Putin
PERSON59 w/ U.S.·4 w/ Eurozone
ET
Emmy Taylor
PERSON61 w/ U.S.·2 w/ Eurozone