Back to People & Entities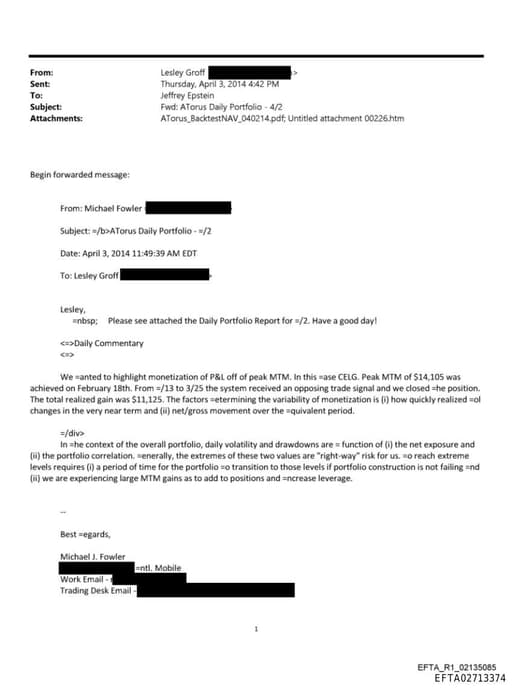
=E
=enerally
Person
1
Total Mentions
1
Documents
0
Connected Entities
Name reference in documents
Document Mentions (1)
EFTA02713374.pdf
1 mentionEFTA02713374
In =he context of the overall portfolio, daily volatility and drawdowns are = function of (i) the net exposure and (ii) the portfolio correlation. =enerally, the extremes of these two values are "right-way" risk for us. =o reach extreme levels requires (i) a period of time for the portfolio =o transition
Sponsored
Connected Entities
No connected entities