Back to Network
5
Shared Docs
5
Same-Page
5 / 5
Mentions
Document Mentions (5 shared documents)
2 mentions1 same-page
Page ?Same page
poration EFTA01397876 for U.S. federal income tax purposes) created or organized in or under the laws of the United States, any state thereof or the District of Columbia; (3) an estate the income of which is subject to U.S. federal income taxation regardless of its source; or (4) a trust which either (i) is subject
rs." Prospective investors should consult their own tax advisors regarding the application of these rules to their investment in the Access Fund. Work-Outs. It is possible that a company in which the Access Fund invests will face financial difficulty, requiring the holder to work-out or otherwise rest
2 mentions1 same-page
Page ?Same page
poration EFTA01395834 for U.S. federal income tax purposes) created or organized in or under the laws of the United States, any state thereof or the District of Columbia; (3) an estate the income of which is subject to U.S. federal income taxation regardless of its source; or (4) a trust which either (i) is subject
rs." Prospective investors should consult their own tax advisors regarding the application of these rules to their investment in the Access Fund. Work-Outs. It is possible that a company in which the Access Fund invests will face financial difficulty, requiring the holder to work-out or otherwise rest
2 mentions1 same-page
Page ?Same page
poration EFTA01396398 for U.S. federal income tax purposes) created or organized in or under the laws of the United States, any state thereof or the District of Columbia; (3) an estate the income of which is subject to U.S. federal income taxation regardless of its source; or (4) a trust which either (i) is subject
rs." Prospective investors should consult their own tax advisors regarding the application of these rules to their investment in the Access Fund. Work-Outs. It is possible that a company in which the Access Fund invests will face financial difficulty, requiring the holder to work-out or otherwise rest
Sponsored
2 mentions1 same-page
Page ?Same page
poration EFTA01395370 for U.S. federal income tax purposes) created or organized in or under the laws of the United States, any state thereof or the District of Columbia; (3) an estate the income of which is subject to U.S. federal income taxation regardless of its source; or (4) a trust which either (i) is subject
rs." Prospective investors should consult their own tax advisors regarding the application of these rules to their investment in the Access Fund. Work-Outs. It is possible that a company in which the Access Fund invests will face financial difficulty, requiring the holder to work-out or otherwise rest
2 mentions1 same-page
Page ?Same page
poration EFTA01397071 for U.S. federal income tax purposes) created or organized in or under the laws of the United States, any state thereof or the District of Columbia; (3) an estate the income of which is subject to U.S. federal income taxation regardless of its source; or (4) a trust which either (i) is subject
rs." Prospective investors should consult their own tax advisors regarding the application of these rules to their investment in the Access Fund. Work-Outs. It is possible that a company in which the Access Fund invests will face financial difficulty, requiring the holder to work-out or otherwise rest
Sponsored
Mutual Connections (78)
Entities connected to both the District of Columbia and Work-Outs
United States
LOCATION162 w/ the·5 w/ Work-Outs
Puerto Rico
LOCATION45 w/ the·5 w/ Work-Outs
European Union
ORGANIZATION41 w/ the·5 w/ Work-Outs
U.S. Virgin Islands
LOCATION36 w/ the·5 w/ Work-Outs
United Kingdom
LOCATION30 w/ the·5 w/ Work-Outs
Eric Holder
PERSON26 w/ the·5 w/ Work-Outs
Denmark
LOCATION22 w/ the·5 w/ Work-Outs
U.S. Treasury Regulations
ORGANIZATION22 w/ the·5 w/ Work-Outs
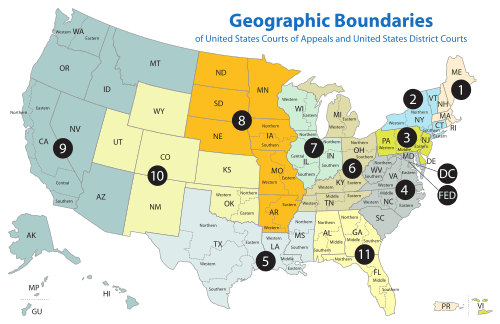
United States District Court
ORGANIZATION22 w/ the·5 w/ Work-Outs
Norway
LOCATION17 w/ the·5 w/ Work-Outs
Finland
LOCATION16 w/ the·5 w/ Work-Outs
Cayman
LOCATION16 w/ the·5 w/ Work-Outs
Belgium
LOCATION15 w/ the·5 w/ Work-Outs
Keogh
ORGANIZATION15 w/ the·5 w/ Work-Outs
Estonia
LOCATION14 w/ the·5 w/ Work-Outs
Cayman Islands
LOCATION14 w/ the·5 w/ Work-Outs
Lithuania
LOCATION13 w/ the·5 w/ Work-Outs
Ireland
LOCATION13 w/ the·5 w/ Work-Outs
Luxembourg
LOCATION12 w/ the·5 w/ Work-Outs
Paul Volcker
PERSON11 w/ the·5 w/ Work-Outs