Back to Network












9
Shared Docs
8
Same-Page
13 / 9
Mentions
Document Mentions (9 shared documents)
4 mentions1 same-page
Page ?Same page
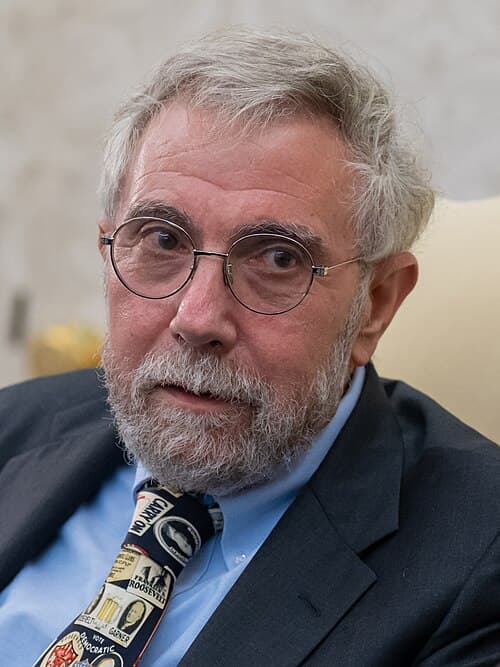
e American economy, Nobel laureate economist Paul Krugman, compared them in his latest article in the New York Times, Pointing Toward Prosperity? As Krugman points out Mitt Romney's five-point plan to restore prosperity is a list of things he claims will happen, with no description of the policies he wou
e both President Obama and Governor Romney are promising that their economic policies will invigorate the American economy, Nobel laureate economist Paul Krugman, compared them in his latest article in the New York Times, Pointing Toward Prosperity? As Krugman points out Mitt Romney's five-point plan to resto
s in 2020, rather than at the clear and pressing problems of the present — a bunch of modest if sensible proposals rather than a big push. Again as Krugman says; a slow job is better than a snow job. Mr. Obama may not be as bold as we'd like, but he isn't actively misleading voters the way Mr. Romney is
emanke understood the depths of the problem early and responded energetically and creatively. The clearest vindication of his actions has been that the European Central Bank, after charting the opposite course for three years with disastrous results, has adopted policies similar to the Fed's — and averted a potential Leh
3 mentions1 same-page
Page ?Same page
ression, they probably won't blame fear, per se. Instead, they'll castigate our leaders for doing the wrong things as a result of unnecessary fear. Krugman: For the overriding fear driving economic policy has been debt hysteria, fear that unless we slash spending we'll turn into Greece any day now. Afte
mption that today's good news somehow is attached to a bad story as negative consequences could begin, not too far in the future. As Nobel Laureate Paul Krugman wrote this week in his op-ed in the New York Times - The Jobless Trap — We are creating a permanent class of unemployed Americans as a result of our
uts and tax increases) self-defeating or the unavoidable response to high budget deficits and debt? Can central banks such as the Federal Reserve or the European Central Bank engineer recovery by holding short-term interest rates near zero and by buying massive amounts of bonds (so-called "quantitative easing")? Or will
2 mentions1 same-page
Page ?Same page
Lhc,Nctu Bork Cr;imcs y 2•1 2012 Austerity, Italian Style By PAUL KRUGMAN Two months ago, when Mario Monti stepped down as Italy's prime minister, The Economist opined that "The coming election campaign will be, above all
th unemployment marching ever higher. The one piece of good news is that bond markets have calmed down, largely thanks to the stated willingness of the European Central Bank to step in and buy government debt when necessary. As a result, a financial meltdown that could have destroyed the euro has been avoided. But that's
Sponsored
2 mentions1 same-page
Page ?Same page
ir balance sheets to record levels to get money to the public markets. At some point, there will have to be a change or there will be consequences. Paul Krugman once said: "Unsustainable situations usually go on longer than most economists think possible. But they always end, and when they do, it's often pai
accountability to all of Europe. Second is the belief that individual countries must control their budgets. And third, there is the conviction that the European Central Bank cannot be allowed to print money to lend to sovereign governments. Many Germans are terrified of runaway inflation because of what it did to their
2 mentions1 same-page
Page ?Same page
he Daily Beast The British Prime Minister Is Coming to America EFTA_R1_00225754 EFTA01840698 Niall Ferguson Article 5 NYT What Greece Means Paul Krugman Article 6 The Moscow Times Jews in Russia Alexei Bayer Article I. Bloomberg Iran-Israel History Suggests a Different Future Pankaj Mishra M
their leaders cannot take until all other options have failed — a state of affairs that, if you ask me, Greece is rapidly approaching. Germany and the European Central Bank could take action to make that extreme step less necessary, both by demanding less austerity and doing more to boost the European economy as a who
2 mentions1 same-page
Page ?Same page
r balance sheets to record levels to get money to the public markets. At some point, there will have to be a change or there will be consequences. Paul Krugman once said: "Unsustainable situations usually go on longer than most economists think possible. But they always end, and when they do, it's often pa
accountability to all of Europe. Second is the belief that individual countries must control their budgets. And third, there is the conviction that the European Central Bank cannot be allowed to print money to lend to sovereign governments. Many Germans are terrified of runaway inflation because of what it did to their
Sponsored
2 mentions1 same-page
Page ?Same page
The National (Abu Dhabi) Qatar's ties with the Muslim Brotherhood affect entire region Ahmed Azem Article 6 NYT Europe: Apocalypse Fairly Soon Paul Kruqman Article 7. Harper's Magazine A pundit's rosy view of the Pax Americana Andrew J. Bacevich AIM:le I Wall Street Journal Total Sanctions Might S
t have to happen; the euro (or at least most of it) could still be saved. But this will require that European leaders, especially in Germany and at the European Central Bank, start acting very differently from the way they've acted these past few years. They need to stop moralizing and deal with reality; they need to s
2 mentions1 same-page
Page ?Same page
r. and lee A. Casey The Washington Post Ryan Crocker's `strategic patience' in Afghanistan Jackson Diehl Article 6. NYT An Impeccable Disaster Paul Krugman EFTA00586772 AniCIC 1. NYT Palestinian Statehood Editorial September 11, 2011 -- A United Nations vote on Palestinian membership would be rui
Barack Obama. EFTA00586786 lo NYT An Impeccable Disaster Paul Krugman September 11, 2011 -- On Thursday Jean-Claude Trichet, the president of the European Central Bank or E.C.B. — Europe's equivalent to Ben Bernanke — lost his sang-froid. In response to a question about whether the E.C.B. is becoming a "bad bank"
Page ?
conditions supportive of growth. While we expect the European Central Bank (ECB) to gradually shift to a more neutral stance
Page HOUSE_OVERSIGHT_014546
gree of certainty; historically, productivity forecasts have been notoriously wrong. In The Age of Diminished Expectations,” first published in 1990, Paul Krugman, Nobel laureate in economics and professor at City University of New York, wrote that the lower pace of productivity growth experienced since the ear
Page: HOUSE_OVERSIGHT_014546 →Page HOUSE_OVERSIGHT_014547
ent low productivity growth rates do not portend low growth rates going forward. Just as Hansen was proven wrong on his secular stagnation theory and Krugman was proven wrong on his diminished expectations for the US economy (and they were both influenced by their pessimistic view on productivity), those w
Page: HOUSE_OVERSIGHT_014547 →Sponsored
Mutual Connections (200)
Entities connected to both Paul Krugman and the European Central Bank
Barack Obama
PERSON46 w/ Paul·20 w/ the
George W. Bush
PERSON33 w/ Paul·18 w/ the
Jeffrey Epstein
PERSON29 w/ Paul·13 w/ the
Marc Rich
PERSON24 w/ Paul·15 w/ the
Bill Clinton
PERSON29 w/ Paul·10 w/ the
United States
LOCATION21 w/ Paul·11 w/ the
Prince Charles
PERSON21 w/ Paul·7 w/ the
Donald Trump
PERSON21 w/ Paul·6 w/ the
Mitt Romney
PERSON20 w/ Paul·7 w/ the
Julie K. Brown
PERSON20 w/ Paul·5 w/ the
Paul Ryan
PERSON21 w/ Paul·4 w/ the
Prince Andrew
PERSON19 w/ Paul·5 w/ the
Bloomberg L.P.
ORGANIZATION20 w/ Paul·4 w/ the
LB
Leon Black
PERSON18 w/ Paul·5 w/ the
Medicaid
ORGANIZATION19 w/ Paul·3 w/ the
United Kingdom
LOCATION9 w/ Paul·13 w/ the
Benjamin Netanyahu
PERSON15 w/ Paul·7 w/ the
Samantha Power
PERSON17 w/ Paul·5 w/ the
Virginia Giuffre
PERSON20 w/ Paul·2 w/ the
George Mitchell
PERSON17 w/ Paul·5 w/ the